What Florida Homeowners Insurance Covers — and What It Does Not
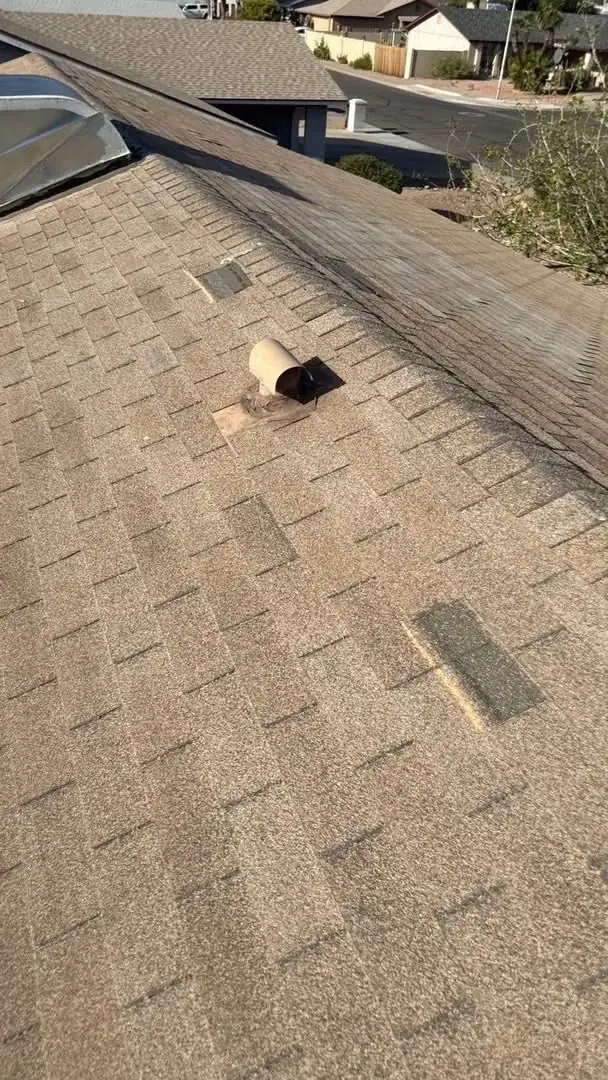
Covered Events
- ✔ Hurricane or tropical storm wind damage
- ✔ Hail damage (including June 2025 Polk County storm)
- ✔ Tornado damage
- ✔ Fallen tree from a covered storm event
- ✔ Lightning strike causing structural damage
Not Covered
- ✗ Normal wear and tear from aging
- ✗ UV degradation or heat damage
- ✗ Pre-existing damage not reported promptly
- ✗ Cosmetic hail damage without structural breach
- ✗ Damage from deferred maintenance or neglect
The 2022 Florida Insurance Reform — What It Changed for Haines City Homeowners
Florida's 2022 property insurance reform (Senate Bill 2-D) made several changes that directly affect roof claims. The most significant: insurers can now pay actual cash value (depreciated) rather than full replacement cost on standard homeowners policies.
What this means in practice: if your 14-year-old architectural shingle roof has depreciated to 40% of its original replacement value, your insurance company can pay 40 cents on the dollar after you pay your deductible. You cover the remaining 60%. Full explanation of the 2022 Florida insurance reform →
The Gap Problem — Read This Before Signing Anything: A real Central Florida case — a homeowner was promised she would only pay her $1,000 deductible. Insurance covered $24,000. The contractor billed $37,000. She owed $13,000 she had not budgeted for and faced a contractor lien on her property. Before signing any roofing contract, get your insurance adjuster's written estimate and confirm in writing who is responsible for any gap. How to protect yourself from contractor insurance misrepresentation →
The 15-Year Florida Roof Rule
Florida Statute 627.7011 protects homeowners: insurers cannot cancel or refuse to renew a policy solely because the roof is under 15 years old. Once a roof reaches 15 years, they can request a condition inspection — but you have the right to hire your own authorized inspector first. If that inspector confirms 5 or more years of remaining useful life, the carrier cannot drop you based on roof age alone.
If you have received a notice from your insurance carrier about your roof's age, call us at (863) 238-1601 before taking action. A free inspection documents your roof's current condition and gives you the information to respond to your carrier. How long roofs last in Haines City's climate →
FAQ — Roof Insurance Claims in Haines City
Request an authorized roof inspection before agreeing to anything. Florida law gives you the right to an independent inspector's assessment before your carrier acts on roof age. If the inspection confirms 5+ years of remaining life, your carrier cannot refuse renewal solely on age. Call us at (863) 238-1601 — we provide free photo-documented inspections that you can share with your insurer.
Yes — significantly in many cases. A new impact-resistant shingle roof or standing seam metal roof reduces your carrier's risk and typically earns a premium discount of 15–30%. After a wind mitigation inspection (which documents your roof's wind resistance to Florida Insurance Code standards), some Haines City homeowners save $800–$2,000 per year. The premium savings often partially offset the installation cost over time. See roof installation cost vs insurance savings calculation →
A licensed public adjuster advocates for you during the claims process and can be worth it on large or disputed claims. However, Florida's 2022 reform caps public adjuster fees. For straightforward claims, thorough photo documentation from a licensed contractor (which we provide on every inspection) is often sufficient. If your claim is denied or significantly underpaid, a public adjuster or attorney experienced in Florida property insurance disputes is worth consulting. Florida insurance reform and your rights →